FINANCIAL PROCESSES
1. FINANCIAL PROCESSES
FINANCIAL PROCESSES
FINANCE SERVICES DIVISION
FINANCE SERVICES DIVISION
GOVERNMENT SERVICE INSURANCE SYSTEM
All government workers under permanent, temporary, or contractual Plantilla positions are mandatorily covered.
Contributions are shared by the employee and DNSC (employer).
Employee Share: 9% of monthly salary
Employer Share (DNSC): 12% of monthly salary
PHILIPPINE HEALTH INSURANCE CORPORATION
Deduction = 5% of salary, shared equally by DNSC and the employee
Salary floor = ₱10,000, ceiling = ₱100,000
So if you earn ₱120,000 monthly, contributions are still based only on ₱100,000 → ₱5,000 total, ₱2,500 deducted from employee.
HOME DEVELOPMENT MUTUAL FUND
Deduction = 2% of salary (if above ₱1,500)
But employee share is capped at ₱200/month, regardless of how high your salary is
Employers usually also contribute 2% capped at ₱200
Members can voluntarily contribute more for bigger dividends.
MONITORING INITIATIVES
PAYROLL SYSTEM
A system that establishes a centralized database to manage and
record clarificatory actions, facilitates the generation of payroll reports, automates the computation of remittances, and generates remittance lists.

MONITORING INITIATIVES
TAX DATA MANAGEMENT SYSTEM
The administration of employee tax-related information involves the computation, analysis, and projection of withholding taxes to ensure accurate and timely deductions in compliance with applicable laws and regulations.

TAX DATA MANAGEMENT SYSTEM
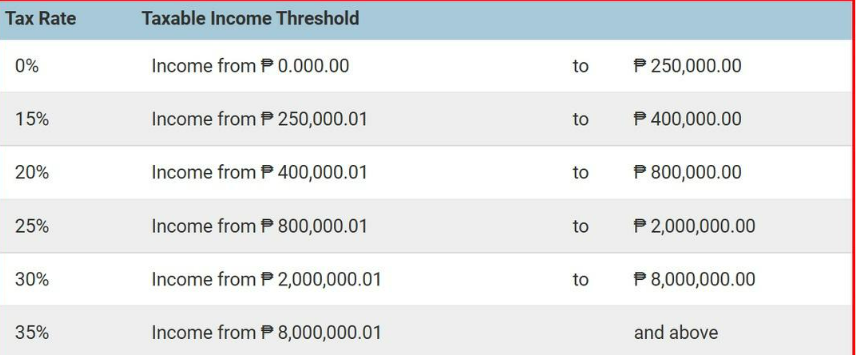
DNSC, as a government employer, is a Withholding Agent—it deducts income tax directly from salaries. Monthly tax withheld is based on the revised BIR tax table effective 2025 (TRAIN Law Schedule 2).
For Job Order (JO) and Contract of Service (COS)
TAX FILING
What to File?
- BIR Form 1701A
(Annual Income Tax Return Individuals Earning Income PURELY from Business/ Profession
[Those under the graduated income tax rates with OSD as mode of deduction OR those who opted to avail of the 8% flat income tax rate])
-Source: BIR RR no. 11-2018 & BIR RMC No. 17-2019
Where to File?
- through eBIRForms v 7.9.5
(Latest version per BIR RMC No. 49-2025)
When to File?
-on of before the Fifteenth (15th) day of April of each year
Covering income for the preceding taxable year. (For CY 2025,Filing should be on or Before April15,2026)
(Source: NIRC Sec. 51 C)
Forms to attach:
- BIR Form 2304
Certificate of Income Payment Not Subject to Withholding Tax
(Excluding Compensation Income)
- BIR Form 2307
Certificate of Creditable Tax Withheld at Source
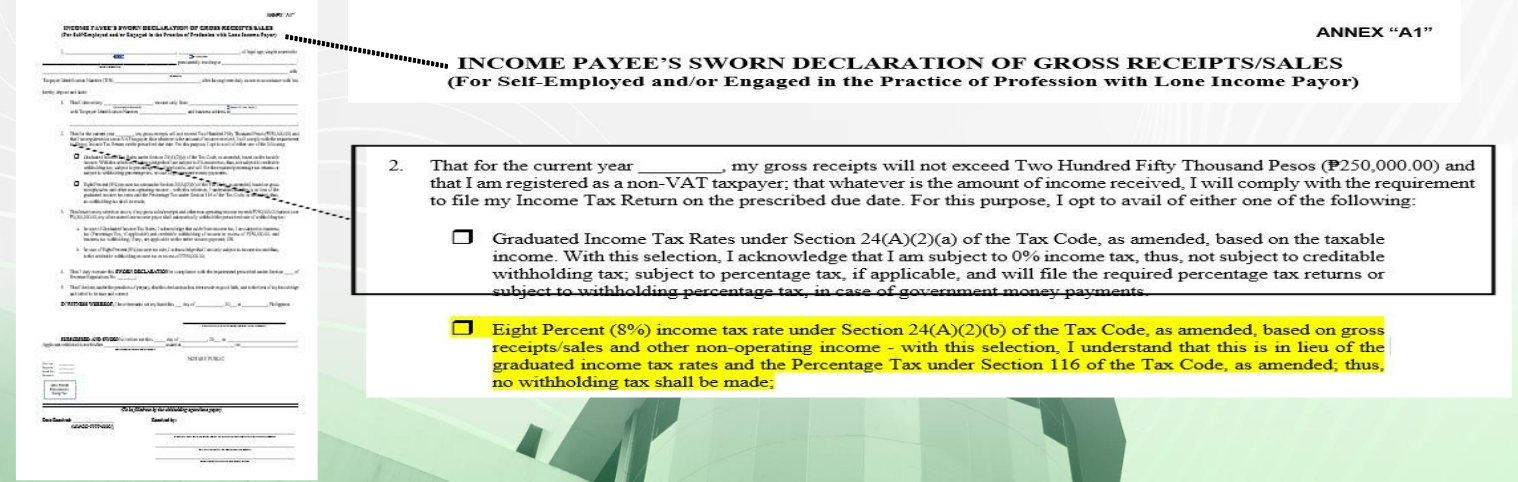
Income Payee’s Sworn Declaration on Gross Receipts/Sales (Annex A-1 of BIR RR no. 11-2018)
(For Self-Employed and/or Engaged in the Practice of Profession with Lone Income Payor)
Definition: A sworn declaration form used by self-employed individuals, professionals (JO/COS), and mixed-income earners to formally opt for the 8% income tax rate on gross receipts in lieu of the graduated income tax rates and percentage tax.
For Plantilla and Casual Employees
not covered in substituted filing
TAX FILING
What to File?
(For previously employed from other company/agency)
BIR Form 1700
Annual Income Tax Return For Individuals Earning Purely Compensation Income
(Including Non-Business/Non-Profession Income)
-Source: BIR RR no. 11-2018 & BIR RMC No. 50-2018
What to File?
(For employees with Mixed Income / previously JO/COS on the same year)
-BIR Form 1701
Annual Income Tax Return Individuals (including MIXED Income Earner), Estates and Trusts
-Source: BIR RR no. 11-2018 & BIR RMC No. 39-2019
Where to File?
- through eBIRForms v 7.9.5
(Latest version per BIR RMC No. 49-2025)
When to File?
- on or before the fifteenth (15th) day of
April of each year
Covering income for the preceding taxable year.
(For CY 2025,Filing should be on or Before April15, 2026)
-Source: NIRC Sec. 51 (C)
Forms to attach:
(with prev. employer / agency)
- BIR Form 2304
Withheld (For Compensation Payment With or Without Tax ` Withheld)
* From both Previous and Current Employer / Agency
Certificate of Income Payment Not Subject to Withholding Tax(Excluding Compensation Income)
Forms to attach:
(with prev. employer / agency)
- BIR Form 2307
Certificate of Creditable Tax Withheld at Source
(mixed Income Earner / prev. JO/COS)
- BIR Form 2316**
Certificate of Compensation Payment/Tax Withheld (For Compensation Payment With or Without Tax Withheld)
** From Current Employer / Agency
Substituted Filing
Definition: The employer(DNSC)takes care of filing the employee’s Annual Income Tax Return (ITR) on their behalf.
Legal Basis: BIR Revenue Regulations No. 11-2018 (TRAIN Law) and Sec. 51-A of the Tax Code.
Who qualifies?
✅ Employee earns purely compensation income from only one employer within the calendar year.
✅ Employer (DNSC) correctly withheld and remitted all income taxes due.
✅ Employee’s income tax liability = tax withheld by employer (no deficiency/excess).
How it works:
DNSC withholds tax every payroll. At year-end, FSD issues BIR Form 2316 (Certificate of Compensation Payment and Tax Withheld).
This Form 2316 serves as the employee’s ITR. No need for the employee to personally file with BIR.
Non-Substituted Filing
Definition:
The employee must personally file an Annual ITR (BIR Form 1700/1701/1701A) with the BIR.
Who must file?
Who must file?
❌ Employees with two or more employers during the year (e.g., transferred jobs)
❌ Employees with business income, sideline/freelance income, or professional practice in addition to their salary (mixed-income earners).
How it works:
Employee files the applicable ITR (usually Form 1700 for compensation earners with two employers, or 1701/1701A for mixed-income).
Deadline: April 15 of the following year.
They must attach Form 2316 and/or Form 2307 from their employers.
DNSC GUIDELINES ON OFFICIAL LOCAL AND FOREIGN TRAVEL
OFFICIAL LOCAL & FOREIGN TRAVEL
OFFICIAL TRAVEL
Official local or foreign travels and assignments shall cover only those that meet the following criteria:
It is essential to the effective performance of an official or employee’s mandates or functions;
It is required to meet the needs of the department, agency, bureau, or office, or there is substantial benefit to be derived by the State;
The presence of the official or employee is critical to the outcome of the meeting, conference, seminar, consultation, or any official activity to be attended; and
The projected expenses are not excessive or involve minimum expenditure.
OFFICIAL LOCAL TRAVEL
Approval of Local Travel
-
The official local travels of the head of the agency, referred to herein as “College President”, in pursuance of the functions of their office, irrespective of the number of days, need not be approved by higher authorities.
-
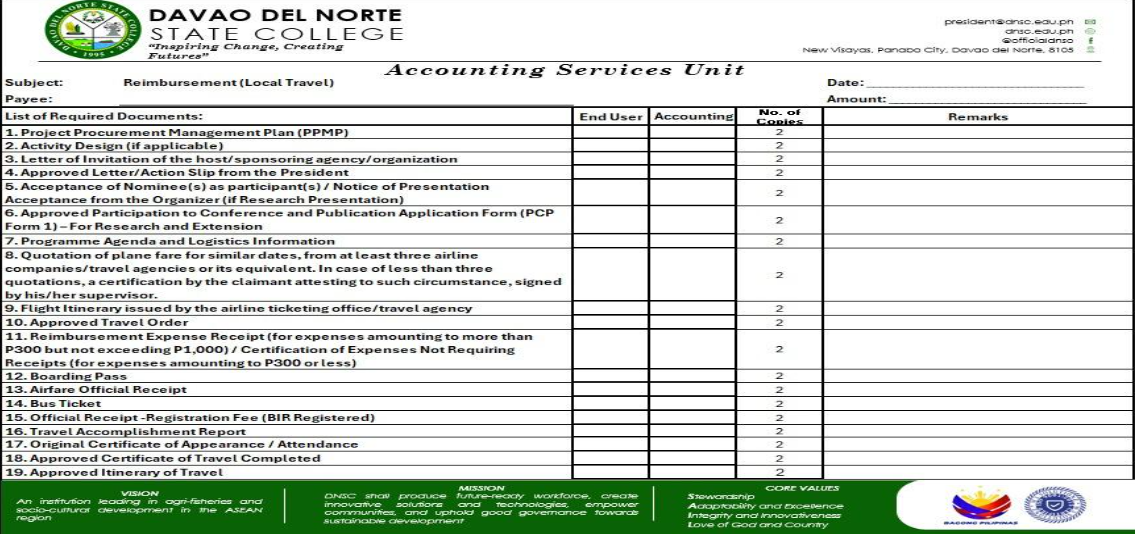
The official local travels of government personnel for less than thirty (30) days and payment of their corresponding travel expenses shall be approved by the College President.
-
The official local travels of government personnel for thirty (30) days or more and payment of their corresponding travel expenses shall be approved by the Chair of the Commission on Higher Education (CHED), or his/her authorized representatives.
Travel Beyond 50-KiIometer Radius from the Permanent Official Station
Official local travel to destinations beyond the 50-kilometer radius from the permanent official station shall be allowed for the following expenses:
1. Transportation Expenses from the permanent official station to the destination or place of assignment.
Furthermore, personnel concerned shall not be entitled to transportation expenses for the entire trip or portion of such trip where a government vehicle was used. If a private vehicle is used, no reimbursement of the cost of gasoline and fuel shall be allowed.
The maximum DTE shall be allowed. However, it may be reduced depending on the availability of funds. Also, claims for payment of DTE shall NOT require the presentation of bills and receipts.
In addition, to preclude double payment, the corresponding portion of the DTE shall NOT BE ALLOWED when the fare paid for transportation includes meals and/or quarters en route, or where meals and/or lodging are part of the cost of the registration fee or paid for or furnished by the government or other parties.
2. Daily Travel Expenses (DTE).
The maximum allowable DTE of government personnel, regardless of rank and position, shall be at the following rates:
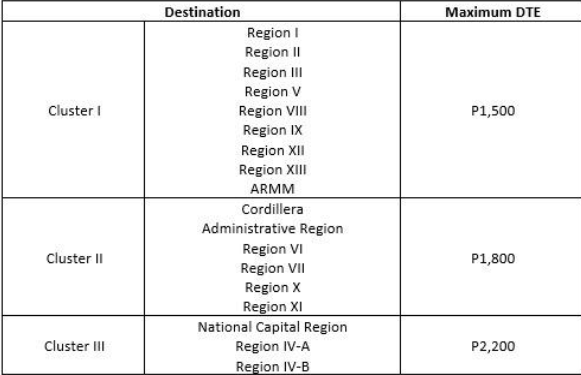
The maximum allowable DTE of government personnel, regardless of rank and position, shall be at the following rates:
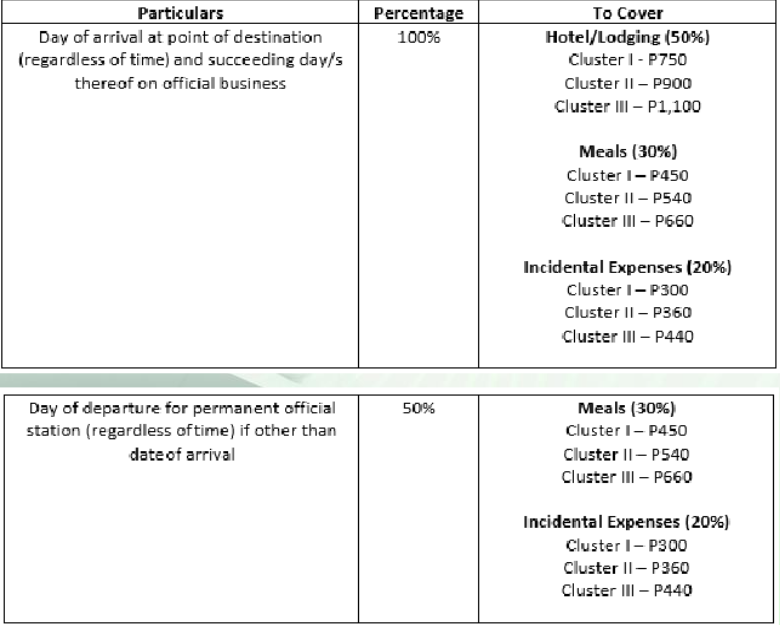
If a government vehicle is used for official local travel, the personnel shall only be entitled to the meal and lodging component of the DTE. In such circumstance, provision for incidental expenses shall not be allowed.
-
The personnel concerned who shall stay in the place of assignment and does not commute daily from the place of assignment to the place of residence or permanent official station and back is entitled to the following expenses:
-
Actual Transportation Expense
-
Daily Travel Expense (DTE) not exceeding the rates provided therein. The claim for hotel/lodging expense shall be substantiated by a hotel bill or invoice to prove that the official or employee stayed in the place of assignment for the whole duration of the official travel.
-
Personnel on official travel who commute daily from the place of assignment to the place of residence or permanent official station shall be allowed the following expenses:
-
Actual fare at the prevailing rates of authorized modes of transportation from the permanent official station to the place of assignment and back.
Presentation of transportation ticket or any equivalent document shall be required as proof of actual travel undertaken. -
Meals in an amount not exceeding thirty percent (30%) of the authorized meal component of the DTE. As applied in the context of DNSC, this is equivalent to Five Hundred Forty Pesos (P540.00) which shall be apportioned based on the following scheme:
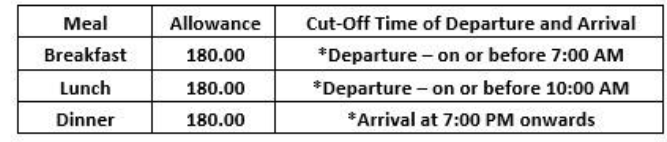
Claims for payment of meal allowance is not required to present bills and receipts. In addition, personnel whose official travel is within Panabo City and Municipality of Carmen is not entitled to an allowance.
Modes of Transportation 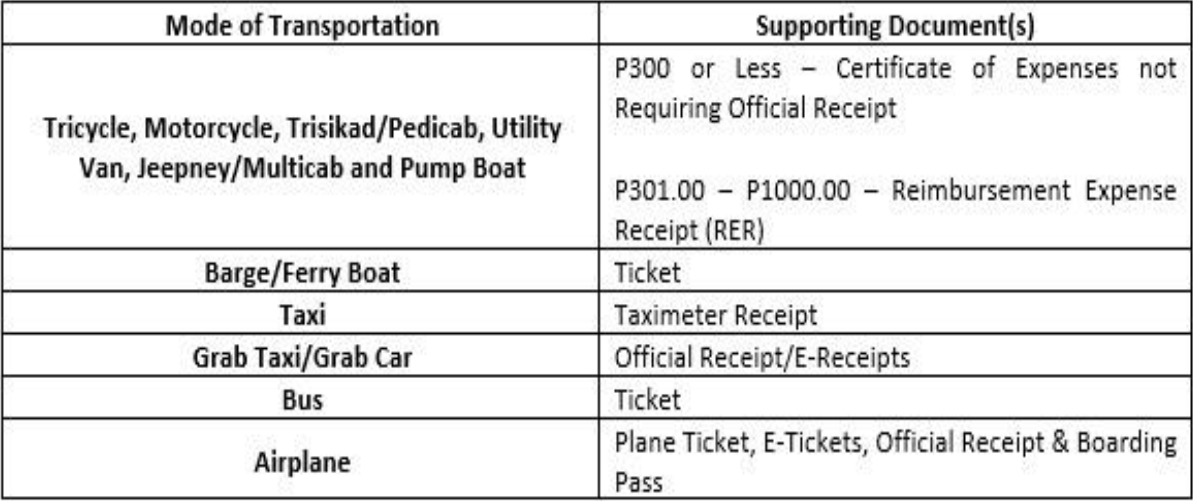
As per NBC563 (Guidelines on Participation of Government Officials and Employees in Conventions, Seminars, Conferences, Symposiaand Similar Non-Training Gatherings Sponsored by Non-Government Organizations or Private Institutions), the following guidelines should be followed:
a. Government officials and employees may be authorized to participate in conventions, seminars, conferences, symposia and such other activities conducted by non-government organizations or private institutions for a fee, as part of the human resource development program of the government, chargeable against government funds.
b. The registration or participation fee in said convention, seminar, etc. shall not exceed P2,800 per day for each participant.
c. Membership and similar fees paid for personal or individual membership in a private organization shall be for the account of the member concerned and shall not be charged to government funds. On the other hand, institutional membership fees, i.e., agency membership may be charged to government funds.
d. As far as practicable, government officials and employees should avail of the early registration rates to avail of reduced costs of participation in conventions, seminars, conferences and the like.
Foreign Travel
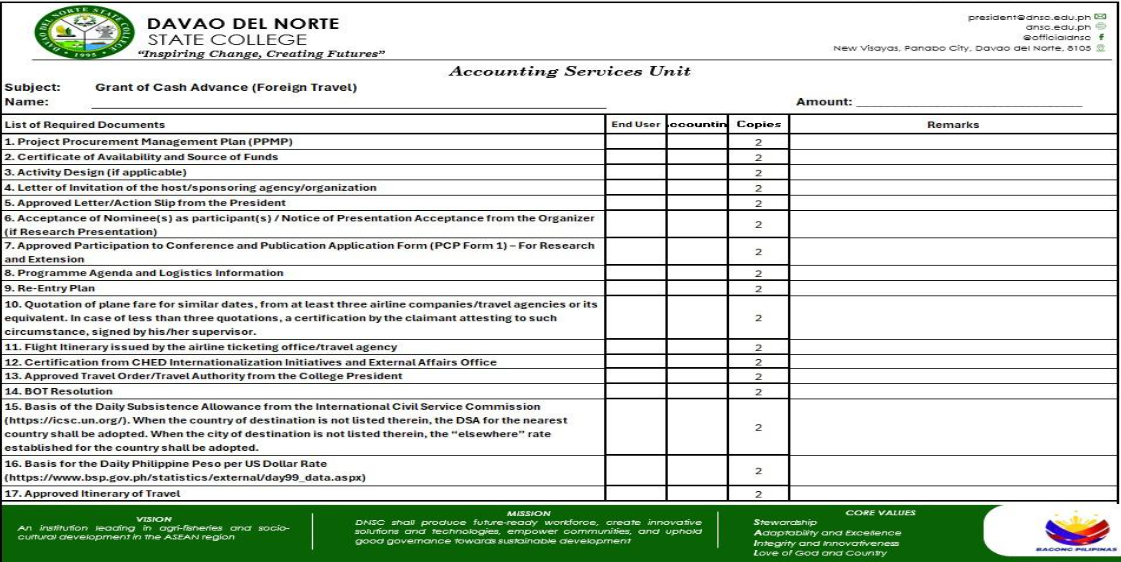
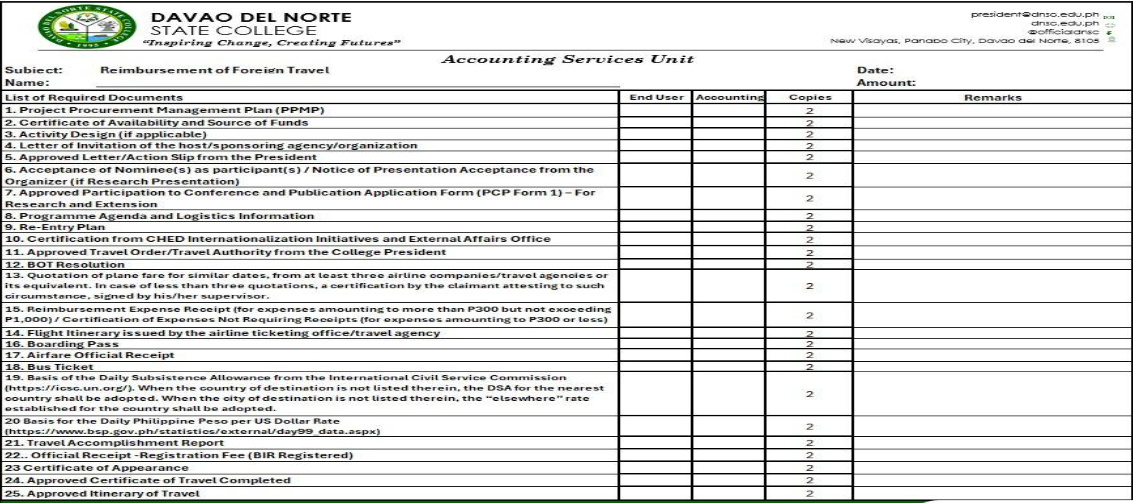
Regardless of length of travels abroad and the number of delegates, official foreign travels and payment of travel expenses of all officials and employees of the College shall be approved by the Board of Trustees upon the recommendation of the International Affairs Staff of Commission on Higher Education (CHED).
Transportation Expenses
In case the officials and employees authorized to travel abroad shall not be provided with transportation by the host country or sponsoring organization, they shall be allowed transportation expenses for the economy class, which for purposes of this Order does not include premium economy class.
Daily Subsistence Allowance
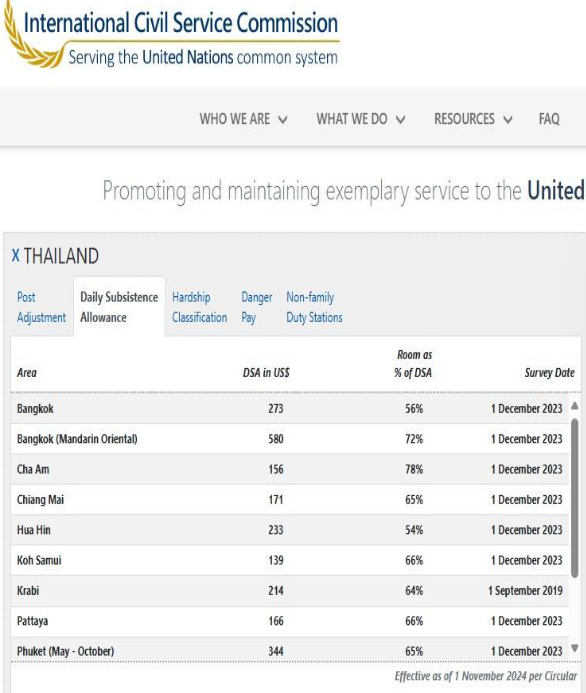
Those who travel abroad shall be granted the DSA based on the daily rates established by the International Civil Service Commission (ICSC) of the United Nations which may be accessed at https://icsc.un.org/. When the country of destination is not listed therein, the DSA for the nearest country shall be adopted. When the city of destination is not listed therein, the “elsewhere” rate established for the country shall be adopted. Furthermore, the DSA rate may be reduced depending on the availability of funds.
If the hotel/lodging, meals, and incidental expenses are provided by the host country of the donor institution, the DSA shall not be allowed.
Claims for payment of DSA shall not require presentation of bills and receipts.
Claims of actual accommodation expenses in excess of the accommodation component of the DSA is not allowed.
FOREIGN TRAVEL
All forms of travel junkets shall be strictly prohibited. The conduct of strategic planning workshops or team-building activities abroad shall not be allowed. The taking of personnel leave immediately before or after the official activity is highly discouraged.
Official foreign trips partially or fully sponsored or funded by private
corporations or private individuals shall be fully disclosed.
No official or personal travel of government officials and employees
shall be funded directly or indirectly, fully or partially, by private individuals,
Including suppliers or contractors, with pending requests/s or
application/s or future dealings with the agency.
LIQUIDATION CASH ADVANCE
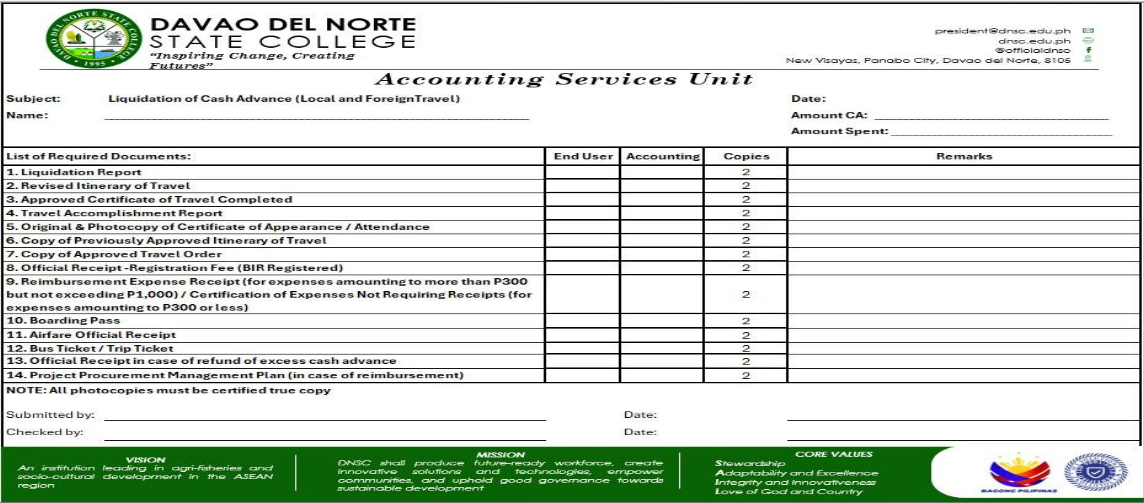
Within two (2) calendar months after the return of an official or employee to the Philippines, in case of official travel abroad, or within one (1) calendar month of his/her return to the permanent official station in the case of official local travel, such official or employee shall render an account of the cash advance received in accordance with existing applicable rules and regulations. However, at yearend, all cash advances shall be fully liquidated regardless of the period of travel as per COA Circular No. 97-002, dated February 10, 1997.
No cash advance shall be granted to any official or employee unless a proper accounting of the previous cash advance given to him/her for travel is first made or the same is first liquidated and/or settled. Failure of the accountable officer to liquidate his cash advance within the prescribed period shall constitute a valid cause for the withholding of his/her salary. Furthermore, violations shall subject the officials or employees concerned to disciplinary action.
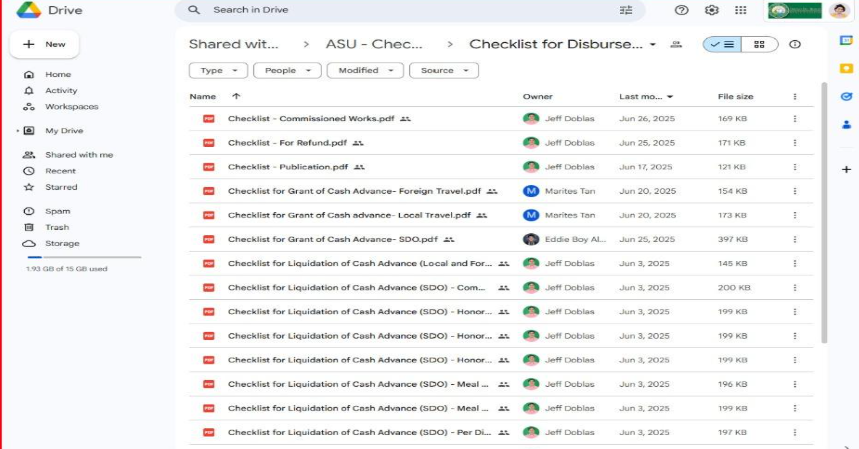
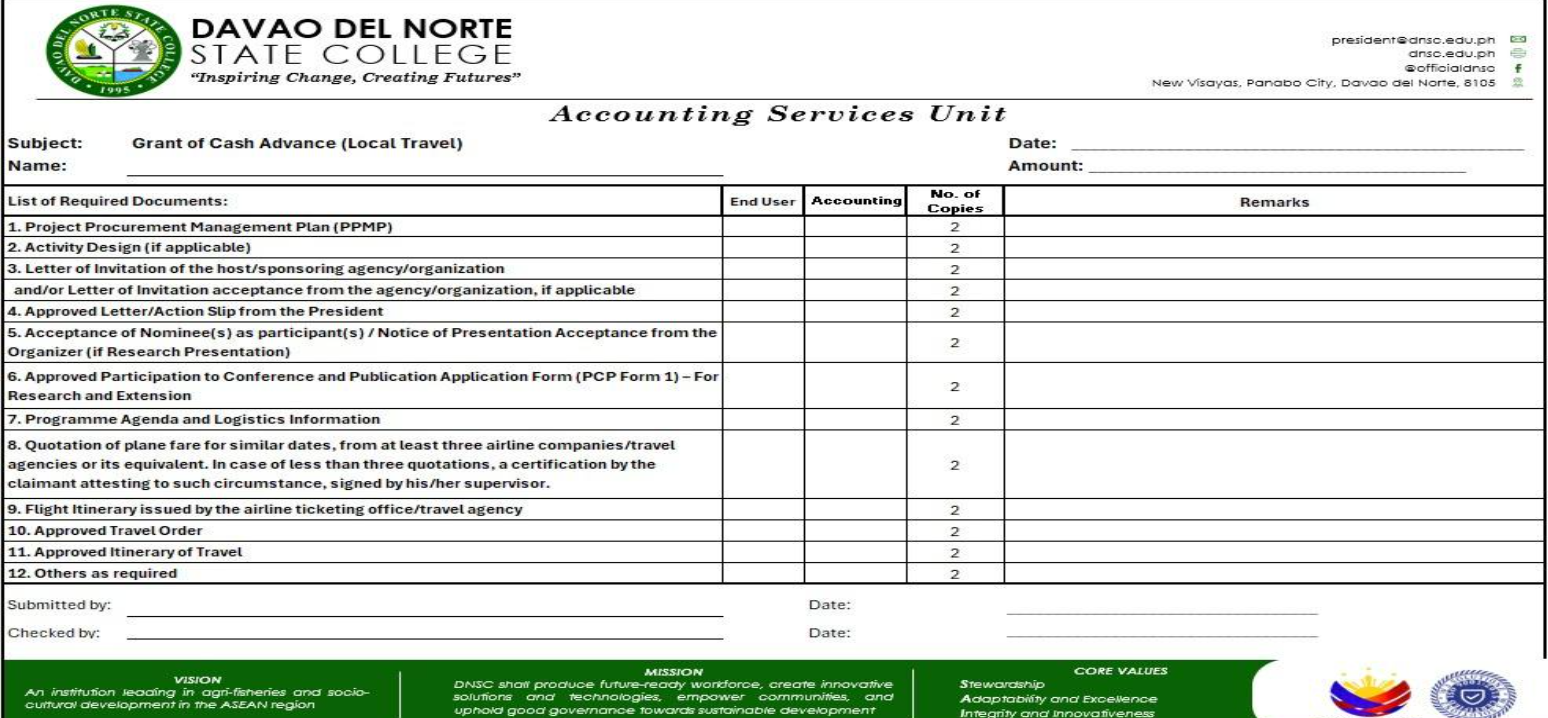
MONITORING INITIATIVES
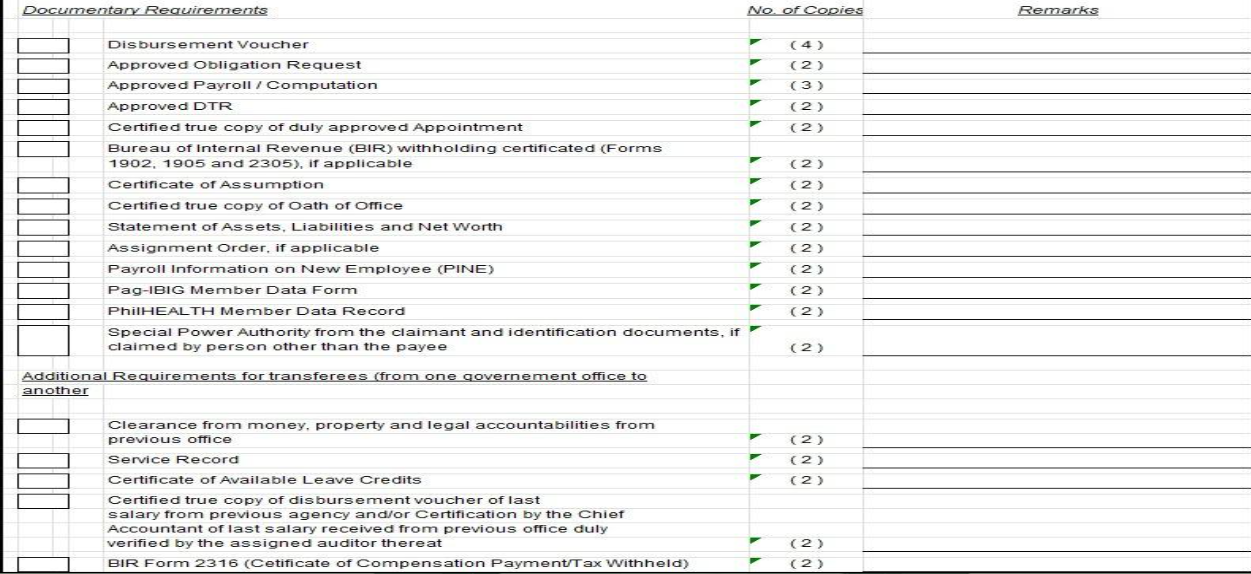
Documentary Requirements for First Salary Plantilla
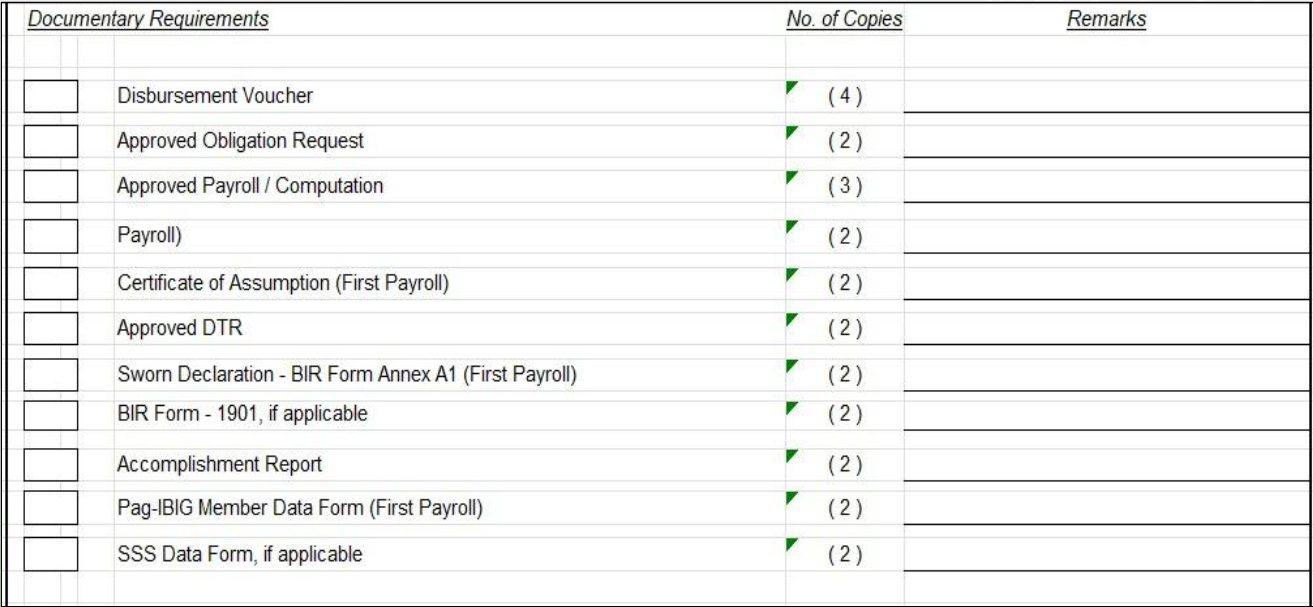
Documentary Requirements for First Salary JO & COS
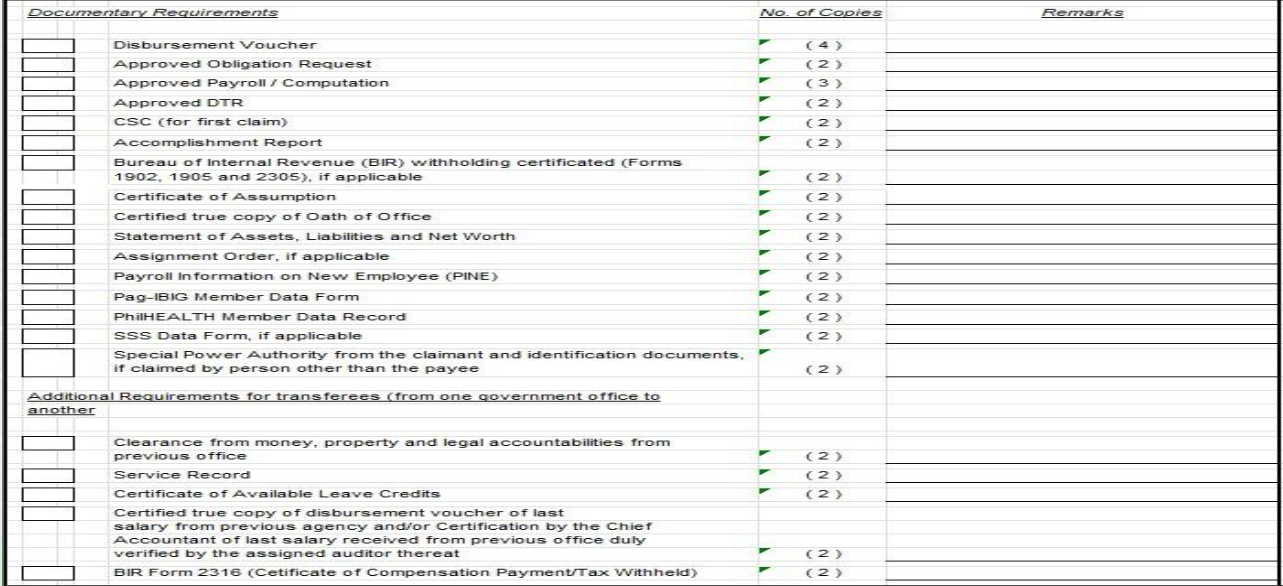
Documentary Requirements for First Salary Casual
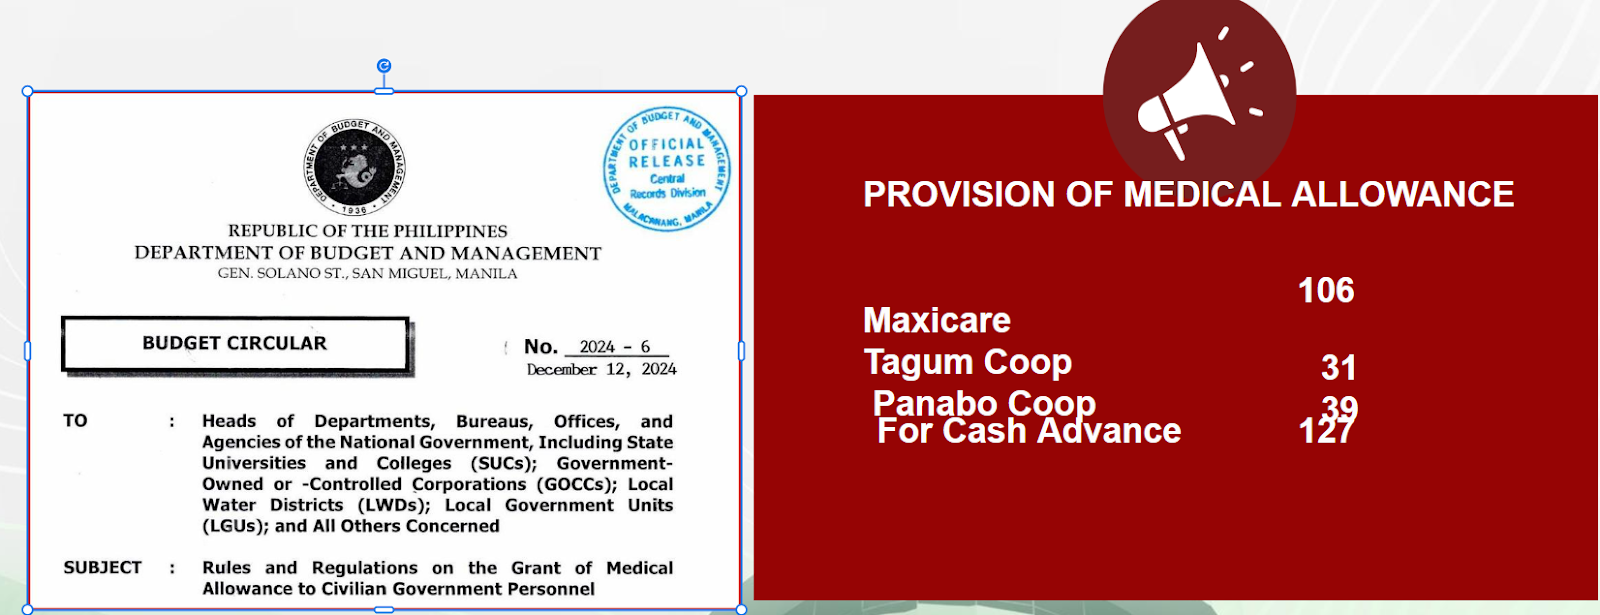
WAYS FORWARD
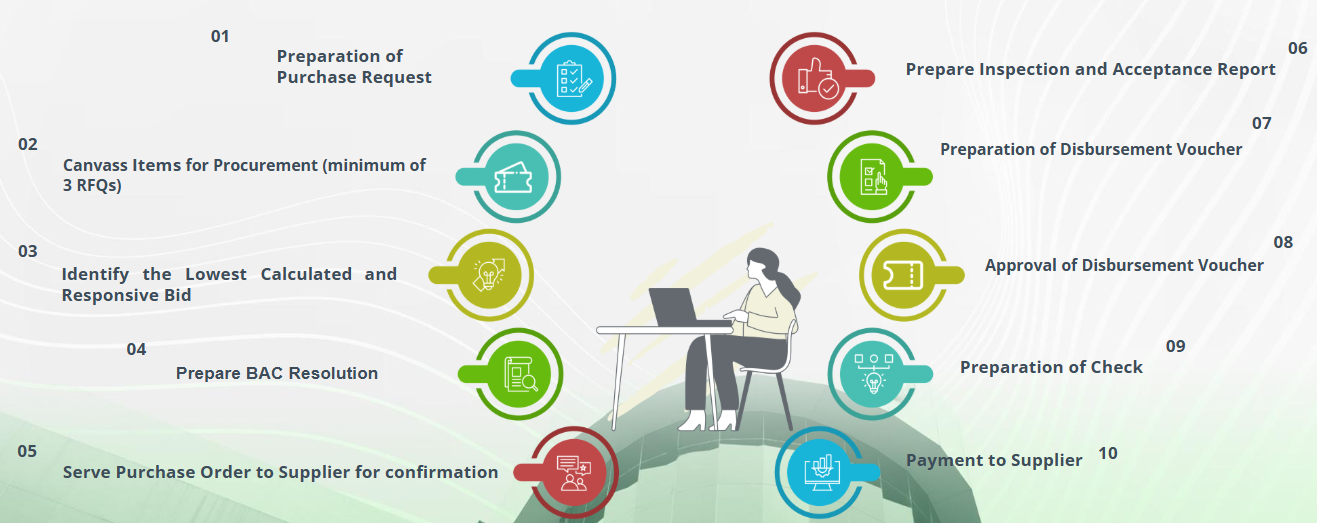
Disbursement Process Flow